Why I Own Google
This is my personal reasoning for why I hold Alphabet. It is not financial advice, and nothing here is a recommendation for anyone else to buy or sell anything. The projections below are simple what-if scenarios, not forecasts.
The short version
Google is the rare company that keeps building the next big business while the old one is still printing money. Search paid for Android, YouTube, Chrome, Cloud, DeepMind, TPUs, and Waymo. Now those bets are turning into businesses of their own. I own it because:
- The core is a cash machine. Search alone did more than $220B in revenue in 2025, and AI Overviews / AI Mode have so far grown usage instead of killing it.
- They own the whole AI stack. Their own chips (TPUs), their own models (Gemini), their own cloud to sell it through, and billions of users across Search, Android, Chrome, Gmail, and YouTube to put it in front of. Very few companies have all of those pieces.
- Cloud went from a money pit to a rocket. Google Cloud lost money as recently as 2022. In Q3 2026 it did $30.7B in a single quarter, up 103% year over year, with a 36% operating margin and a $561B backlog.
- Free options. Waymo, the SpaceX and Anthropic stakes, Isomorphic Labs, and quantum computing are all things I don’t have to pay much for at today’s price, but any one of them could matter a lot.
- The track record. Since the 2004 IPO, GOOGL has turned every $1 into about $119 (24.0% a year) vs 11.1% a year for the S&P 500.
What they’ve done before
Google has a habit of building or buying something that looks small or weird at the time and then turning it into a category leader.
| Year | Milestone |
|---|---|
| 1998 | Larry Page and Sergey Brin found Google out of a Stanford research project (PageRank). |
| 2000 | AdWords launches. Search ads become the business model that funds everything else. |
| 2004 | IPO at $85 a share (about $2 split-adjusted). Gmail launches with a crazy 1 GB inbox. |
| 2005 | Buys Android for roughly $50M. Google Maps launches. |
| 2006 | Buys YouTube for $1.65B, which a lot of people called an overpay. |
| 2008 | Launches Chrome and the first Android phone. |
| 2014 | Buys DeepMind. |
| 2015 | Reorganizes into Alphabet, splitting Google from the Other Bets. |
| 2016 | Reveals the TPU, its own AI chip. AlphaGo beats Lee Sedol. |
| 2017 | Google researchers publish “Attention Is All You Need,” the transformer paper behind basically every modern AI model. |
| 2018 | Waymo launches the first commercial robotaxi service in Phoenix. |
| 2023 | Google Brain and DeepMind merge. Gemini launches. |
| 2024 | First ever dividend. AlphaFold co-creators win the Nobel Prize in Chemistry. |
| 2025 | Revenue passes $400B for the first time. Loses the ad tech antitrust case, but the search case remedies stop well short of a breakup. |
| 2026 | Cloud more than doubles. Waymo raises $16B at a $126B valuation. SpaceX IPO hands Alphabet a huge gain on its early stake. Ad tech judge also declines a breakup. |
A YouTube that cost $1.65B now does more than $60B a year in revenue. An Android that cost about $50M runs most of the phones on the planet. That is the pattern I am betting continues.
What they do now
Alphabet reports three segments:
- Google Services: Search, YouTube, Android, Chrome, Maps, Play, Gmail, Pixel, and subscriptions (YouTube Premium, Google One, YouTube TV). This is the vast majority of revenue and profit.
- Google Cloud: Google Cloud Platform, Workspace, Gemini for businesses, and now selling TPU systems directly. The fastest growing part of the company.
- Other Bets: Waymo, Verily, Wing, and others. Still losing money, but this is where the long-dated upside sits.
Revenue and profit, 2015 to 2025
Over the last ten reported years, revenue grew about 18.3% a year and operating income about 20.9% a year, so the business got bigger and more profitable (a 32% operating margin in 2025). That red line is the one everyone is arguing about right now, more on that below.
Google Cloud
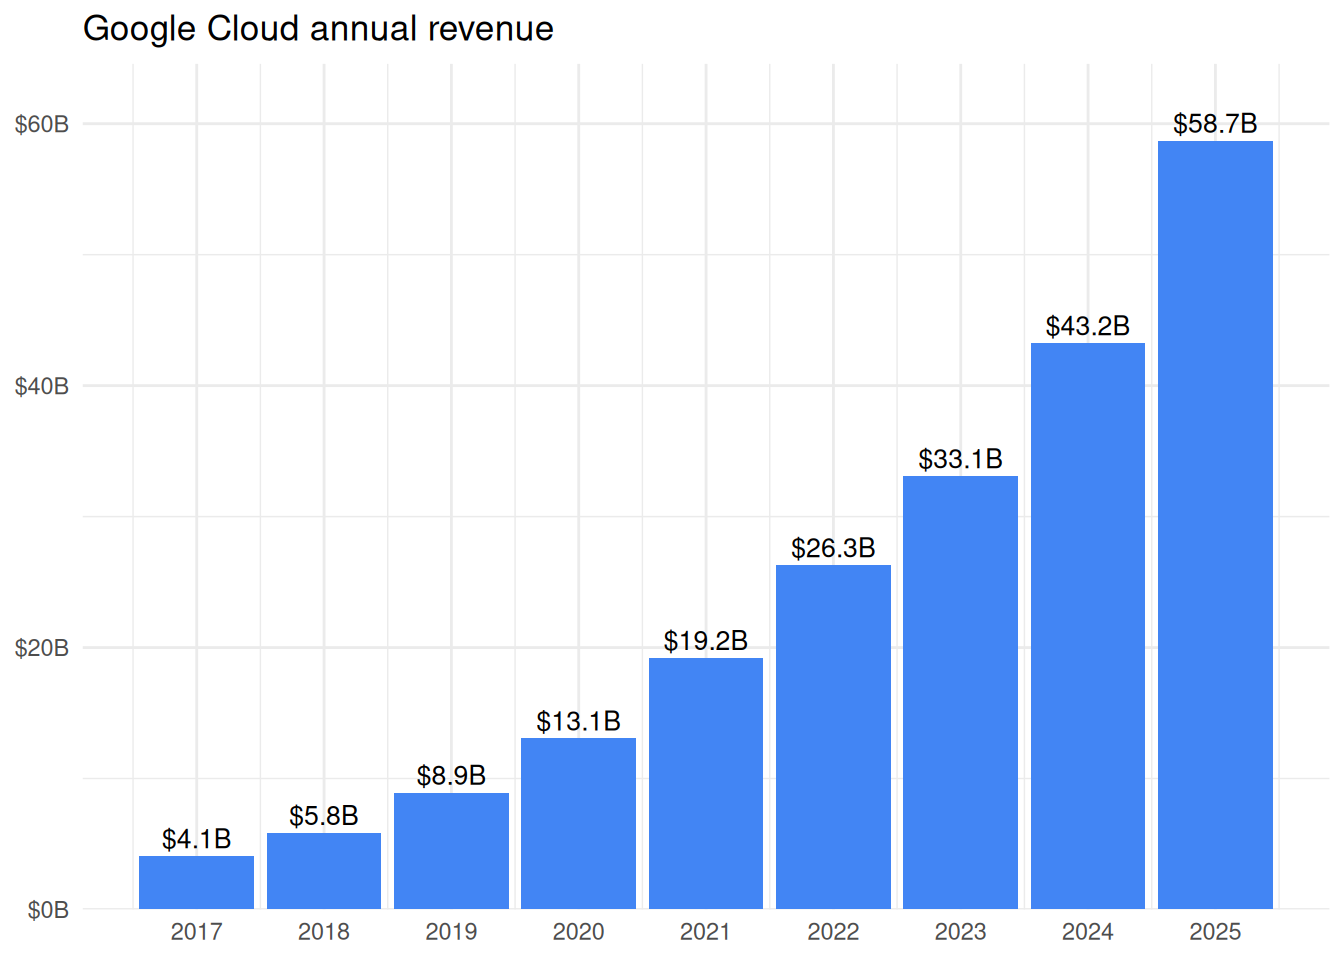
And 2026 is on a different curve: Cloud grew 63% in Q1, 82% in Q2, and 103% in Q3, when it did $30.7B in one quarter. Management says just over half of the $561B backlog should turn into revenue over the next two years, and they are still capacity constrained (they are renting third-party compute to keep up).
Returns vs the S&P 500
These are total returns using adjusted closing prices, so dividends are reinvested. SPY stands in for the S&P 500.
| Window | $10k in GOOGL is now | GOOGL per year | $10k in SPY is now | SPY per year |
|---|---|---|---|---|
| 1 year | $10,645 | 6.5% | $11,346 | 13.5% |
| 5 years | $20,113 | 15.0% | $17,255 | 11.5% |
| 10 years | $79,282 | 23.0% | $40,784 | 15.1% |
| 15 years | $194,640 | 21.9% | $78,078 | 14.7% |
| Since IPO (Aug 2004) | $1,189,101 | 24.0% | $103,370 | 11.1% |
Growth of $10,000 since the IPO
It has not been a smooth ride. The worst peak-to-trough drop was -65% (bottoming in November 2008), and the stock fell about 13% in a single day after Q3 2026 earnings. Right now it sits 26% below its all-time high. Owning it means sitting through stretches like that.
Where it could go
Nobody knows, including me. So instead of a price target, here are three simple scenarios for what the stock could return per year from today’s price, and why each one could happen.
| Scenario | Per year | Price in 5 years | Price in 10 years | $10k in 10 years | What has to happen |
|---|---|---|---|---|---|
| Bear | 2.0% | $327 | $361 | $12,190 | The capex binge does not pay back, AI chatbots eat into Search, and the market pays a lower multiple for a slower, more capital-heavy company. |
| Base | 11.0% | $498 | $840 | $28,394 | Low-teens earnings growth as Cloud keeps compounding and Search grows high single digits, with the valuation roughly flat. |
| Bull | 18.0% | $677 | $1,548 | $52,338 | Cloud and TPUs become an AWS-sized business, AI Mode monetizes as well as classic Search, and Waymo starts to show up in the numbers. |
| Last 10 years’ pace | 23.0% | $833 | $2,347 | $79,350 | Just repeat what actually happened over the last decade. |
The base case is roughly “earnings growth plus a small dividend.” The historical pace is there as a reality check: matching the last decade again from a company this size would be hard, which is why I don’t use it as my base case.
What could go wrong
I’d be lying to myself if I skipped this part.
- The capex bill. Alphabet expects to spend $195 to $205B on capex in 2026 and said 2027 will be significantly higher. Free cash flow went negative in Q2 and Q3 2026, which Google investors are not used to seeing. If AI demand cools, that is a lot of servers to depreciate.
- Dilution. To fund the buildout, Alphabet announced an ~$85B equity raise in June 2026 (including $10B from Berkshire Hathaway), part of it sold gradually through an at-the-market program, and bought back no stock in the first nine months of 2026. A company that used to shrink its share count every year is now issuing shares.
- Search disruption. Search growth slowed to 12% in Q3 2026 from 17% the quarter before (management blamed mostly FX and a World Cup-inflated Q2). If people get answers from chatbots and AI Mode does not monetize as well as ten blue links, the core business shrinks.
- Antitrust. Courts have found Google an illegal monopolist in both search and ad tech. So far the remedies are behavioral (no forced sale of Chrome, Android, or AdX), but appeals are still running in the US and Europe is still weighing its options.
- Noisy earnings. Huge gains and losses on the SpaceX and Anthropic stakes now swing GAAP net income by tens of billions a quarter (a $99B gain in Q2 2026, an $8.7B loss in Q3), so headline EPS is less useful than it used to be. Operating income is the number to watch.
Why I’m still in
Every one of those risks is real, but they mostly come from Google spending heavily into the biggest technology shift since mobile, from a position of owning the chips, the models, the cloud, and the distribution. I would rather own the company placing that bet than the ones it is placing it against.
Sources
- Alphabet quarterly earnings releases (Q4 2025, Q1 to Q3 2026) and annual 10-K filings for the financials table, in particular the Q4 2025 release, the Q3 2026 release, and the June 2026 equity raise announcement.
- Price history from Yahoo Finance, refreshed weekly.
- Coverage of the Q3 2026 results, the Q2 2026 SpaceX gain, and the ad tech remedy ruling.